From Digital Assets to AI Compute: Our Latest Market View
Updated: 1 day ago
September 2026
Dear Investors,
August was defined by rate policy. Softer jobs and inflation data initially pared expectations of a Fed hike, but Chair Warsh's hawkish Jackson Hole message and rising oil prices after US strikes on Iranian targets put hikes back on the table into September, and the S&P 500 and Nasdaq gave back ground in the second half of the month.
Digital assets did the heavy lifting regardless. Bitcoin surged 22% in its strongest week on renewed momentum behind the Clarity Act and a proposed SEC capital raising framework for crypto issuers, topping $81,000 before settling near $77,700, while Ether climbed from roughly $1,880 to $2,420 and Solana traded back above $100. Crypto equities rode the rally, with Coinbase and Robinhood posting double digit weekly gains, and the AI data center story continued to rerate the mining group, even as rate sensitive quantum and long duration names lagged.
Notably, the rally arrived without a volatility regime change: Bitcoin's 30 day realized volatility fell below the Nasdaq's in August, a pattern we read as constructive base building.

Portfolio Activity
We used August's strength to rotate rather than add risk. Across our portfolios:
Rotated profits from digital asset into AI compute infrastructure: we trimmed our Hyperliquid, Solana staking, and Bitcoin ETF positions into strength and recycled proceeds into Core Scientific, IREN, and Keel Infrastructure, deepening our exposure to the data center buildout inside the mining sector. We exited our remaining Marathon position, preferring to hold the theme through stronger operators with better capital structures.
Consolidated our Ether exposure for optionality: we swapped our staked Ether ETP into the iShares Ethereum ETF (ETHA), which carries a deep listed options market, keeping economic exposure intact while making the position eligible for call writing.
Launched yield-seeking and downside-buffer overlay: we wrote covered calls during the period at strikes reasonably above spot. The overlay strategy intends to tactically add yield, annualizing at approximately 3-6% per year, while its premiums also cushions drawdowns; strikes are set well out of the money so the core upside thesis remains intact. We are managing these positions opportunistically when premiums appear attractive relative to our core short-term views.
Market View & Outlook
As we look into the final months of the year, we summarize our forward-looking view as follows:
AI token demand is exponential, and margin rotation favors compute providers.
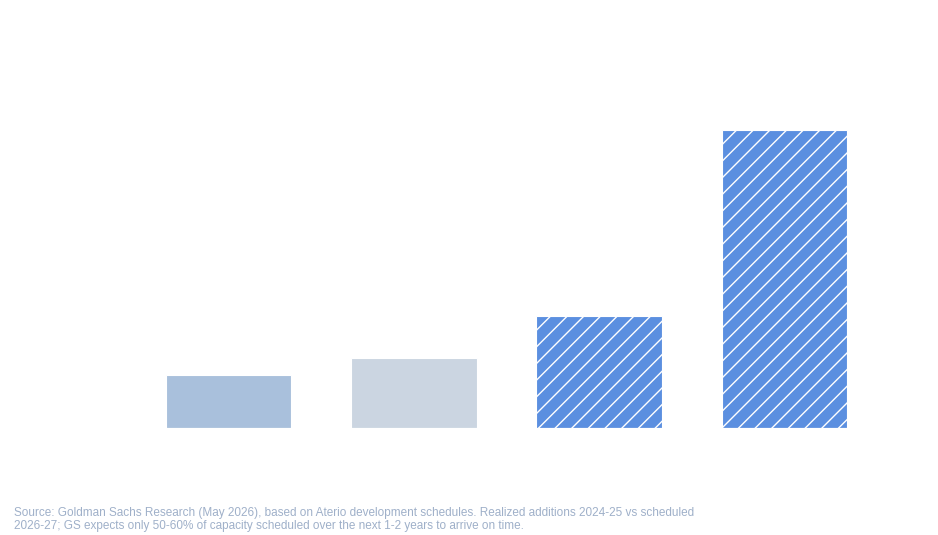
OpenRouter's weekly volume hit 25 trillion tokens in May, five times the level of six months earlier, with agents now consuming roughly five times what humans do, and GenAI cloud spend is up 15 to 20x across every customer cohort in 18 months. Yet the frontier labs keep missing their own margin targets as inference costs run ahead of plan, while only 8.5 GW of US data center capacity actually came online in 2025 against 36.3 GW scheduled for 2027. Demand compounds in months, supply in years. Tokens switch freely between models; every token still needs the same compute. We expect the economics to rotate toward compute providers, and we are positioned in the compute infrastructure part of the stack.

Autonomous agents will transact on crypto rails, and tokenized assets are where they will trade
Agents need to pay for data, APIs, and compute in amounts too small for many legacy networks; Coinbase's x402 protocol processed 169 million stablecoin payments in its first year and is now natively supported inside AWS Bedrock agents. In parallel, tokenized asset trading is scaling faster than the asset base: tokenized stock volume in Q1 2026 alone exceeded all of H2 2025, and RWA perpetuals did $525 billion in Q1 versus $313 billion for the whole of 2025. Agents that transact plus markets that never close compound trading volume, and every trade settles across the exchange, custody, and stablecoin infrastructure we hold.

Bitcoin realized volatility has compressed below the Nasdaq's, following its least volatile year on record. Digital asset volatility points to a cycle bottom.
Bitcoin's volatility compression, multi year lows in leverage and participation, and repeated absorption of selling at support are what base formation looks like to us, and VanEck counts 8 of 12 capitulation signals fired with a likely cycle low in June. We do not attempt to time the market but we see current levels (and slightly below) as the floor for this cycle, and thus continue to maintain core positions, and collect option premium while we wait.
If you would like to discuss any of our current market observations, please reach out to us via email.
Copyright © 2026 BIT Asset Management AG – All rights reserved.
This is an advertising document. This material has been prepared by BIT Asset Management AG for informational purposes only for the sole use of the intended recipient. It does not seek to make any recommendation to buy or sell any particular security or to adopt any specific investment strategy. This document does not contain information material to an investor’s decision to invest in a product. The information should not be regarded by recipients as a substitute for using their own judgment. Neither BIT Asset Management AG nor any of its affiliates, or their directors, officers, or employees, accepts any liability for any loss arising from the use of the information in this document. Data therein should not be relied upon as such information is subject to change, without notice, at the discretion of BIT Asset Management AG at any time. Investors in crypto assets are subject to the risk of total loss of the amount invested. Crypto assets are highly volatile and may fluctuate extremely in a short period of time. Crypto assets may become illiquid depending on trading platforms or investment product. Therefore, crypto assets are high-risk investments and you should not invest in this asset class unless you understand and can bear the risks involved with such investments. Although certain information has been obtained from sources believed to be reliable, we do not guarantee its accuracy, completeness or fairness. We have relied upon and assumed without independent verification, the accuracy and completeness of all information available from public sources.
BIT Asset Management AG is a manager of collective assets authorised by the Swiss Financial Market Supervisory Authority (“FINMA”) under the Financial Institutions Act (“FinIA").


